For years, plenty of ACA Bronze and Catastrophic plans failed the classic high deductible health plan (HDHP) tests - their out-of-pocket maximums were too high, or they paid non-preventive benefits before the statutory deductible. The One Big Beautiful Bill Act (OBBBA) changed that. For months beginning after December 31, 2025, Bronze and Catastrophic plans described in ACA section 1302 that are available as individual coverage through an Exchange are treated as HDHPs for HSA purposes. IRS Notice 2026-5 is the playbook for how that works in practice.
This article answers the question Reddit and Marketplace shoppers keep asking in 2026: "Can I open and fund an HSA on a Bronze plan?" It is not a full Direct Primary Care explainer (see the DPC + HSA guide) and not a redo of 2026 contribution limits or the 2027 limits update.
Quick Answer
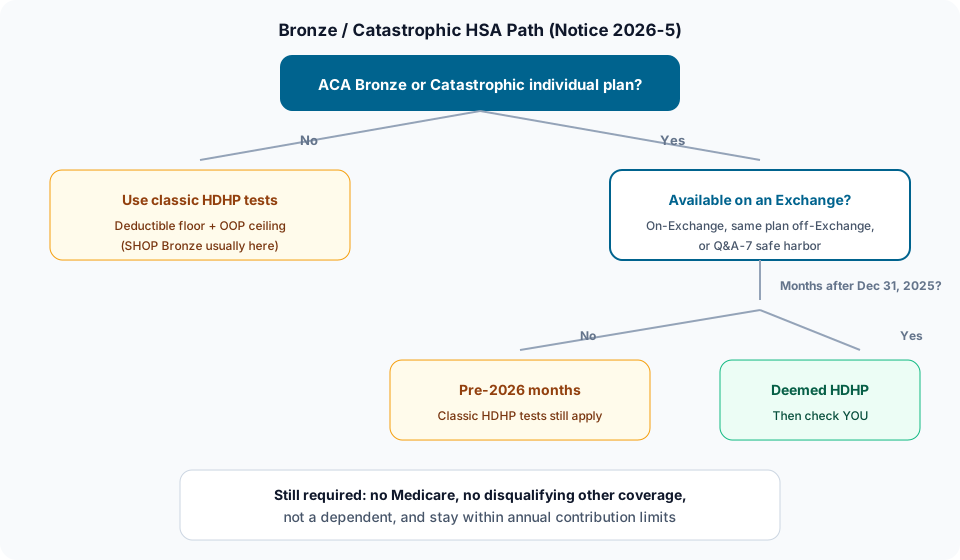
- Yes - often. For months after Dec 31, 2025, qualifying Bronze and Catastrophic individual coverage that is available through an ACA Exchange is treated as an HDHP even if it fails the usual section 223 deductible / out-of-pocket tests.
- You still must be an eligible individual overall: no Medicare, not a dependent on someone else's return, and no disqualifying other coverage (for example a general-purpose FSA).
- Off-Exchange Bronze/Catastrophic can qualify when the same plan is available on an Exchange; the IRS also gives a practical safe harbor if you have no reason to believe it is unavailable on an Exchange.
What Changed Under OBBBA
Section 71307 of OBBBA amended Code section 223(c)(2) so that "high deductible health plan" includes any plan described in ACA section 1302(d)(1)(A) (Bronze) or section 1302(e) (Catastrophic) that is available as individual coverage through an Exchange established under ACA section 1311 or section 1321.
Effective timing: months beginning after December 31, 2025 - so calendar-year 2026 is the first full year most people will use this rule.
Why it mattered: Before OBBBA, many Bronze plans blew the HDHP out-of-pocket cap or paid non-preventive care too early. Catastrophic plans typically offered three primary-care visits before the deductible and used OOP maximums above the HSA statute. Those designs are now deemed HDHPs when the Exchange-individual-coverage conditions are met.
Do Classic Deductible and OOP Tests Still Apply?
For these deemed Bronze/Catastrophic HDHPs: no. Notice 2026-5 Q&A-4 says a Bronze or Catastrophic plan is treated as an HDHP even if it does not satisfy the minimum annual deductible or maximum out-of-pocket requirements in section 223(c)(2)(A).
You still need the plan to be the right kind of Bronze/Catastrophic individual coverage. Employer SHOP Bronze is generally not swept in automatically (Q&A-8) unless the plan independently meets classic HDHP tests - though an ICHRA can be used to buy qualifying individual Bronze/Catastrophic coverage (Q&A-5).
On-Exchange vs Off-Exchange
How Notice 2026-5 treats common enrollment paths:
- Bronze/Catastrophic bought on HealthCare.gov or a state Exchange: Yes - treated as an HDHP if it is ACA Bronze or Catastrophic individual coverage.
- Same plan bought off-Exchange: Yes - if the same plan is available as individual coverage through an Exchange (including certain identical off-Exchange CSR-load variants).
- Individual-market Bronze/Catastrophic you reasonably believe is Exchange-available: IRS sound-administration safe harbor - you may be treated as eligible if you have no reason to believe it is not available on an Exchange (Q&A-7).
- SHOP (small-employer) Bronze: Generally no under the new deemed rule; the plan must meet classic HDHP tests on its own.
Metal Level Is Not an Automatic HSA Badge
Do not assume every plan labeled "Bronze" on a salesperson's spreadsheet qualifies. Confirm it is ACA Bronze or Catastrophic individual coverage meeting Notice 2026-5, and that you have no other disqualifying coverage. Ask the issuer for written HSA-eligibility confirmation for your enrollment months.
Catastrophic Plan Enrollment Limits Still Exist
Catastrophic plans remain restricted under the ACA (generally under age 30, or certain hardship / affordability exemptions). OBBBA did not turn every cheap high-deductible policy into a Catastrophic plan. If you cannot enroll in Catastrophic coverage, this deeming rule does not invent eligibility for you - look at Bronze or a traditional HDHP instead.
What Else You Must Still Satisfy
Treating the plan as an HDHP is only half of HSA eligibility. You must also:
- Have no disqualifying other health coverage (general-purpose FSA/HRA traps still apply; limited-purpose and post-deductible designs may be OK).
- Not be enrolled in Medicare for the months you want to contribute (see Medicare Part A and HSA eligibility).
- Not be claimable as a dependent on another taxpayer's return.
- Stay inside the annual contribution ceiling for your coverage type (2026 limits; 2027 limits).
Mid-year Marketplace switches still raise proration and last-month rule questions - a Bronze start on July 1 does not automatically unlock a full-year contribution without running those rules.
Last-Month 10% Tax Is Not the 6% Excess Tax
If you use the last-month rule after a mid-year Bronze start, failing the testing period can mean income inclusion plus a 10% additional tax. That is different from the recurring 6% excise tax on excess contributions left in the account (Form 5329). Keep those tracks separate.
ICHRA and Employer Angles
Notice 2026-5 clarifies that using an employer individual coverage HRA (ICHRA) (or certain other premium-only HRAs) to buy Bronze/Catastrophic individual coverage does not by itself stop that plan from being treated as an HDHP. The HRA generally must stay in a form that does not itself become disqualifying other coverage (premium-only designs are the usual safe pattern - get plan counsel).
If you later leave HDHP-eligible coverage but keep an HSA balance, you can often still spend the account even when you can no longer contribute - see what happens when you leave your HDHP.
Related OBBBA HSA Changes (Pointers Only)
Notice 2026-5 also covers:
- Permanent telehealth safe harbor for HDHPs (plan years beginning after Dec 31, 2024).
- Direct primary care service arrangements that meet the statutory definition and fee caps - deep coverage lives in our DPC guide, not here.
Frequently Asked Questions
Bottom Line
For 2026 and beyond, many Marketplace Bronze and Catastrophic plans are finally HSA-compatible by statute, even when old deductible and out-of-pocket math would have failed. Confirm Exchange-individual status (or the Notice 2026-5 off-Exchange safe harbors), scrub other coverage, and then fund up to the annual limit. When open enrollment hits, pair this page with the 2027 contribution limits and the last-month rule guide so you do not mix tax years or eligibility shortcuts.
Primary sources: Notice 2026-5; Publication 969; ACA section 1302 Bronze/Catastrophic definitions as cited in the notice.
Written by
Michael is a Certified Public Accountant and IRS Enrolled Agent who has spent 12 years helping individuals and businesses navigate tax-advantaged health accounts. He leads HSA Orbit's tax strategy content.